Longonjo
Operator: Pensana
Mixed rare earth carbonate, ~20 ktpa planned; construction since 2025 (reported).
- Production
- First production 2027 (target)
- Export route
- Lobito Corridor
- Documentation
- Public sources
Demonstration dataListings, lots and offers shown are samplesAbout sample data

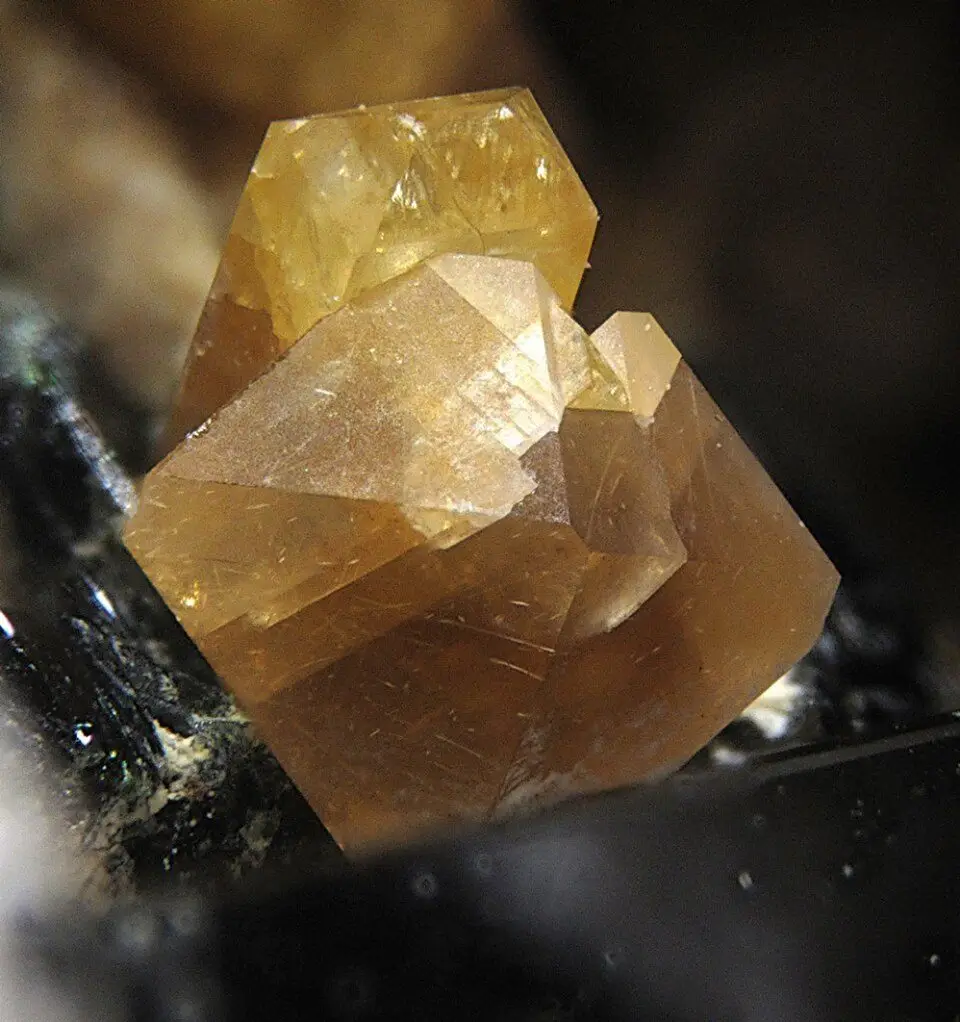
Reference specimen · Ra'ike (see also: de:Benutzer:Ra'ike), CC BY-SA 3.0
Rare earths
Top-10 #3Sample dataThe light rare earths neodymium (Nd) and praseodymium (Pr), traded together as 'NdPr', are the key ingredients of NdFeB permanent magnets used in EV motors, wind turbines, robotics, drones and defence systems. China controls about 60–70% of mining and around 90% of separation and magnet making, and has used export controls since 2023–25. Africa has a strong pipeline of carbonatite and monazite deposits, mostly in construction or development in 2026. Early African output will be concentrate or mixed carbonate, not separated oxide.
Controlled supply
This mineral is subject to radioactive cargo handling. Offers are published only after ARAM has reviewed the supporting documents, and some details are visible to verified companies only.
Verified companies only
Volumes, origins and terms are shown to verified companies. Availability for everyone else: Pre-production pipeline. Verify your company or submit a request.
Rare earth mineral concentrate
Unit: kg · HS 2846.90
monazite or bastnäsite concentrate (e.g. Kangankunde monazite ~55–60% TREO); monazite carries thorium (radioactive)
Mixed rare earth carbonate (MREC)
Unit: kg · HS 2805.30
hydrometallurgical intermediate, ~42–55% TREO depending on spec (e.g. Longonjo); priced on its NdPr (and Dy/Tb) content
Separated oxides
Unit: kg · HS 2530.90
NdPr oxide (≈75% Nd2O3 / 25% Pr6O11, ≥99% (Nd+Pr)/TREO), plus La, Ce (low value, oversupplied)
Metals and alloys
Unit: kg
NdPr metal and NdFeB alloy (downstream, outside Africa)
ARAM sourcing assessment
Top strategic demand. The play is future offtake: linking African projects to Western separators and magnet makers. Listing status: Pre-production pipeline (with first-production dates), Contract for Kangankunde/Phalaborwa as they start.
Angola
Longonjo (Pensana) — construction, first MREC targeted 2027, ~20 ktpa MREC
Malawi
Kangankunde (Lindian) — mining started, first monazite concentrate targeted end-2026; Songwe Hill (Mkango) — development
Tanzania
Ngualla (Peak Rare Earths) — large high-grade bastnäsite deposit, timeline unconfirmed; Wigu Hill
South Africa
Phalaborwa (Rainbow Rare Earths) — REEs from phosphogypsum stacks; Steenkampskraal — historic high-grade monazite mine; Zandkopsdrift (Frontier)
Uganda
Makuutu (ionic clay, more HREE-weighted)
Kenya
Mrima Hill (Nb-REE, undeveloped)
USGS Mineral Commodity Summaries 2026 — African rows of the world production & reserves table
World Mine Production and Reserves: Significant revisions were made to the 2024 production for Australia, Madagascar 121,400 122,700 NA Nigeria 1,500 1,500 NA South Africa — — 860,000 Tanzania — — 890,000 World total (rounded) 380,000 390,000 >75,000,000
| Year | Country | HS | Value | Net weight |
|---|---|---|---|---|
| 2023 | South Africa | 253090 | $94.5m | 414.4 kt |
| 2024 | South Africa | 253090 | $59.2m | 954.5 kt |
| 2023 | South Africa | 284690 | $6.3m | 280 t |
| 2024 | South Africa | 284690 | $5.5m | 287 t |
| 2024 | South Africa | 280530 | $528k | 29 t |
| 2023 | Tanzania | 253090 | $222k | 477 t |
| 2023 | South Africa | 280530 | $163k | 8 t |
Mirror data fills gaps where exporters report late or incompletely.
| Year | Buyer | Origin | HS | Value | Net weight |
|---|---|---|---|---|---|
| 2024 | China | South Africa | 253090 | $150.9m | 972.8 kt |
| 2023 | China | South Africa | 253090 | $102.8m | 300.1 kt |
| 2024 | Rep. of Korea | South Africa | 253090 | $8.0m | 18.7 kt |
| 2023 | Rep. of Korea | South Africa | 253090 | $7.0m | 17.3 kt |
| 2023 | Japan | South Africa | 253090 | $5.5m | 14.0 kt |
| 2023 | USA | South Africa | 284690 | $5.2m | 212 t |
| 2024 | USA | South Africa | 284690 | $4.4m | 214 t |
| 2024 | Japan | South Africa | 253090 | $2.2m | 6.4 kt |
| 2023 | China | Tanzania | 253090 | $2.0m | 2.8 kt |
| 2023 | China | Uganda | 253090 | $1.8m | 5.7 kt |
| 2023 | Japan | Uganda | 253090 | $638k | 1.7 kt |
| 2024 | China | Tanzania | 253090 | $549k | 1.3 kt |
Source: UN Comtrade (public data). Values in US$.
Minerals trade on formula prices: a published benchmark × metal content × payable percentage, less treatment charges and impurity penalties, settled on independent assay. Payment is typically by documentary letter of credit, with 90–95% provisional payment against shipping documents and the balance on final assay.
Request terms for Rare Earths — Light (NdPr)Cross-border
No special restriction
National mining codes with state participation (Tanzania free-carried interest; Malawi Mines & Minerals Act 2023)
Primary source
Cross-border
Permit / licence
Radiation-protection licensing for monazite (national nuclear regulators)
Primary source
Cross-border
No special restriction
China's export controls on REE processing technology and some REEs push Western buyers to ex-China supply
Primary source
Operator: Pensana
Mixed rare earth carbonate, ~20 ktpa planned; construction since 2025 (reported).
Operator: Lindian Resources
Monazite concentrate; mining started, ore stockpiled (reported).
Operator: Mkango Resources
Carbonatite NdPr project.
Operator: Peak Rare Earths
Large high-grade bastnäsite deposit; timeline unconfirmed.
Operator: Rainbow Rare Earths
Rare earths recovered from phosphogypsum stacks.
Products: mixed rare earth carbonate (MREC, Chinese spec ~42–44% TREO; some Western MREC ~55% TREO), monazite/bastnäsite concentrate, and separated NdPr oxide (≈75% Nd2O3 / 25% Pr6O11; (Nd+Pr)/TREO ≥99% per GB/T 31965-2015). NdPr oxide priced US$/kg (SMM, Asian Metal, Fastmarkets); US DoD-backed floor of US$110/kg referenced for MP Materials.
Source 1 · stanfordmaterials.comSource 2 · metal.comSource 3 · asianmetal.com
Project status (reported mid-2026, verify with company releases): Longonjo (Pensana, Angola) under construction since 2025, first MREC targeted 2027, ~20 ktpa MREC; Kangankunde (Lindian, Malawi) mining started, first monazite concentrate targeted end-2026; Songwe Hill (Mkango, Malawi) development; Ngualla (Peak Rare Earths, Tanzania) large undeveloped deposit, timeline unconfirmed; Phalaborwa (Rainbow, South Africa) recovering REEs from phosphogypsum stacks.
Source 1 · lindianresources.com.auSource 2 · miningweekly.comSource 3 · ecofinagency.comSource 4 · barchart.com
Research compiled September 2026 from USGS, UN Comtrade, producer and regulator publications. Facts marked “reported” come from secondary sources and should be confirmed before contracting.
On the ground · Rare Earths — Light (NdPr)
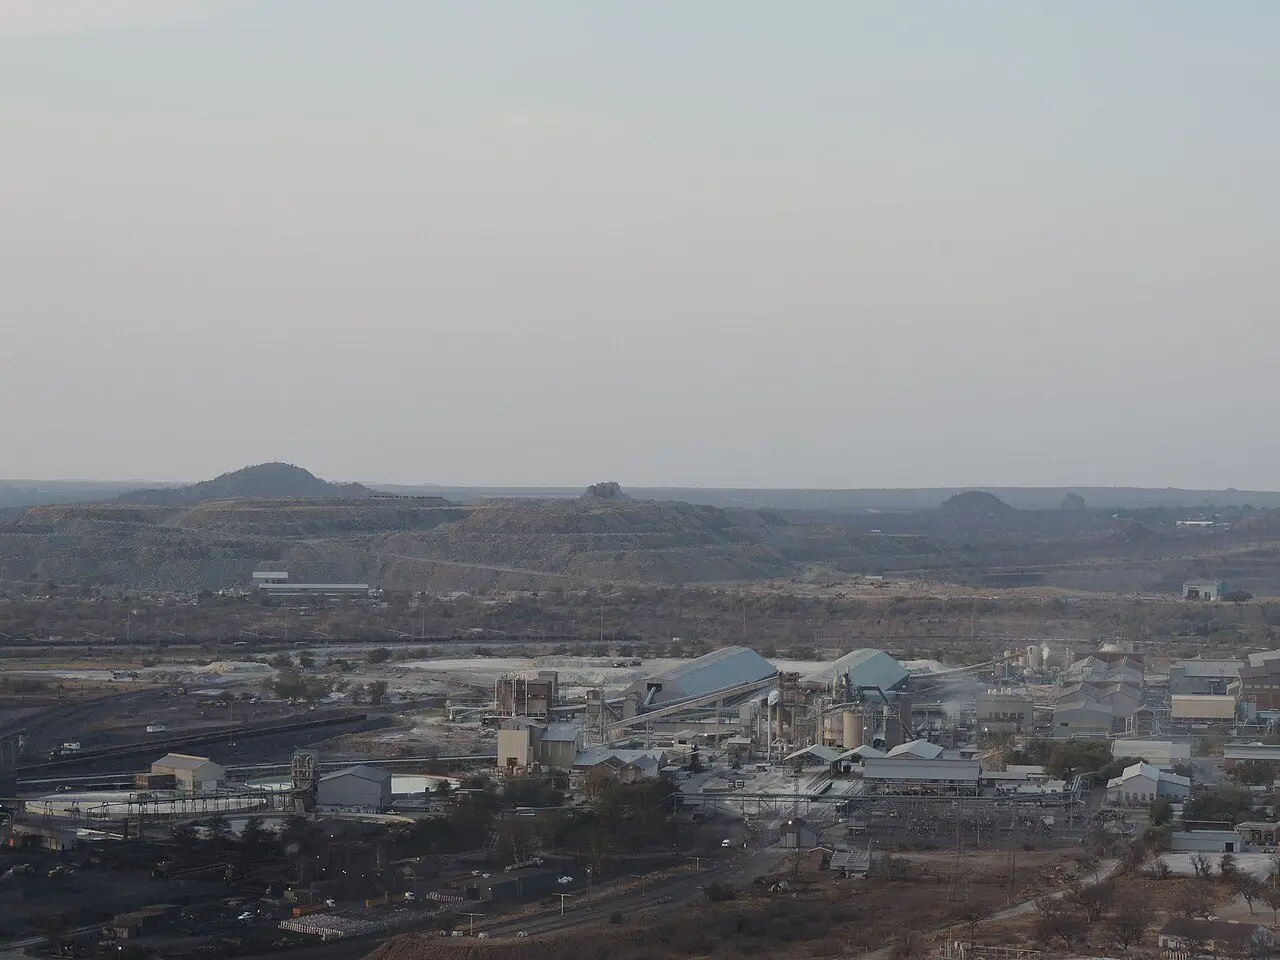
The mines and districts that define supply, with their operators. They are shown for geographic context: third-party operations, not ARAM sites, and not the source of any particular lot. Ownership and status as publicly reported in 2026.
Mining complexSouth Africa
Operated by Palabora Mining Company; Foskor; Rainbow Rare Earths (phosphogypsum project)
A carbonatite complex hosting one of Africa's largest open pits (copper), phosphate operations (Foskor) and rare earths recoverable from phosphogypsum stacks.
Photo: Daniel Kraft · CC BY-SA 3.0South Africa
No freely licensed photograph
South Africa
Operated by Steenkampskraal Holdings
A historic high-grade monazite mine in the Western Cape, once a thorium and rare-earth producer, now being redeveloped.
Ra'ike (see also: de:Benutzer:Ra'ike), CC BY-SA 3.0
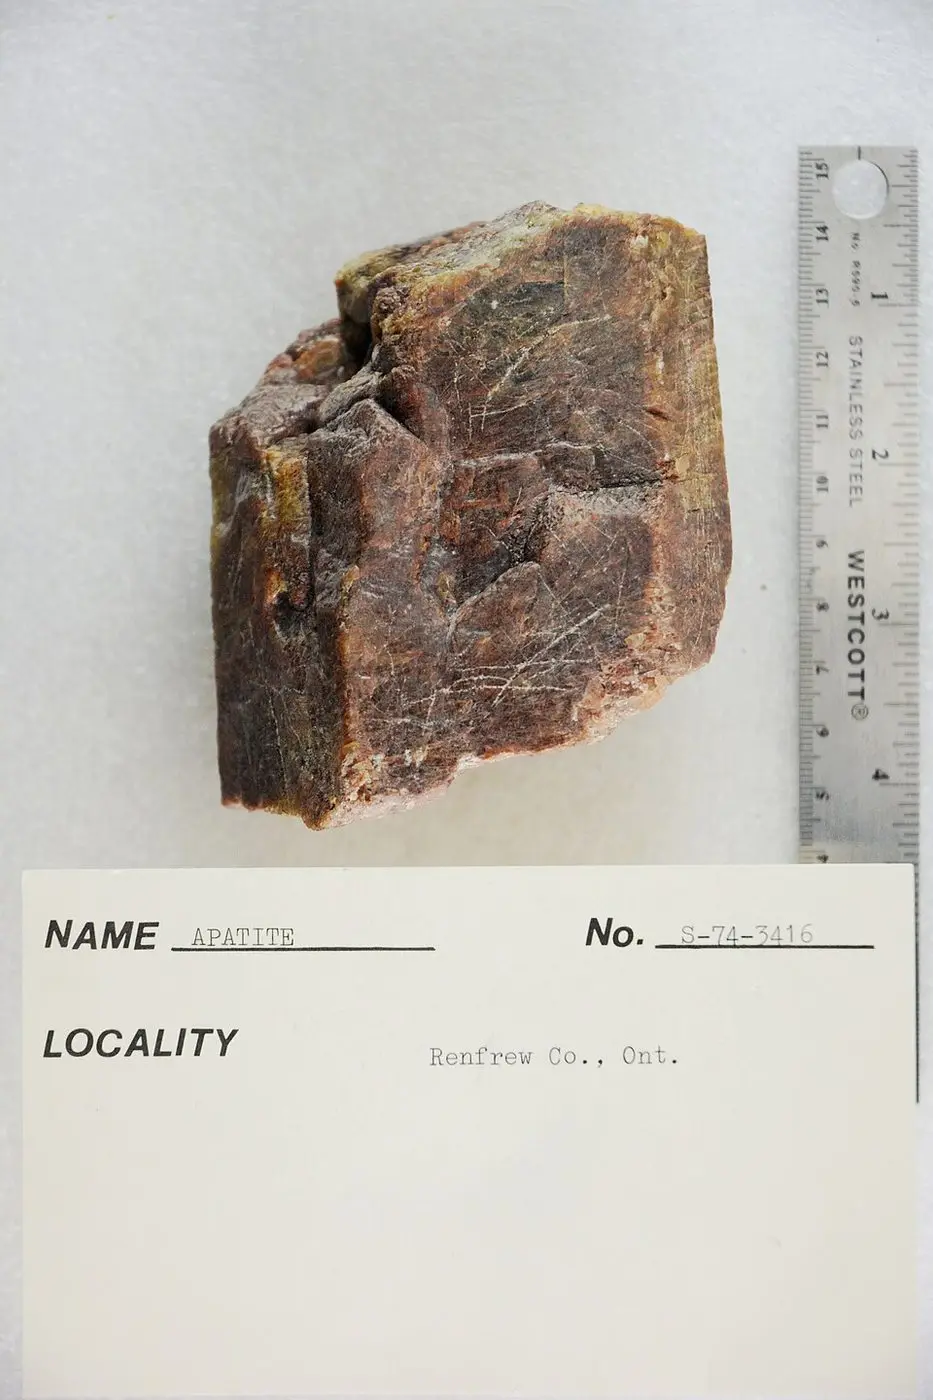
Kelly Nash, CC BY 3.0
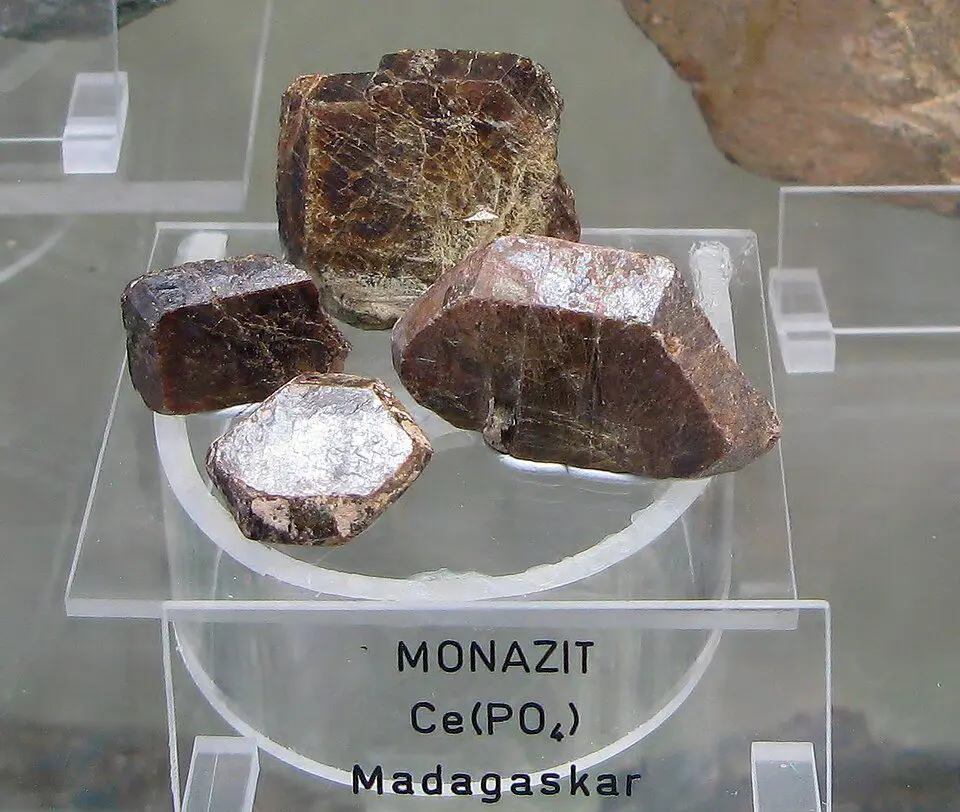
Robert M. Lavinsky, CC BY-SA 3.0
Reference specimens of the ore minerals and products, from public collections. They illustrate the material, not a specific ARAM lot or source.

Rare earths
The heavy rare earths dysprosium (Dy) and terbium (Tb) are added to NdFeB magnets so they keep working at high temperatures, as in EV motors and military systems. They are far scarcer than NdPr. China, plus Myanmar ionic clays processed in China, supplies almost all of them, and China restricted Dy/Tb and other medium/heavy REEs from April 2025. Africa's best heavy-REE prospects are Lofdal (Namibia, xenotime) and Makuutu (Uganda, ionic clay).

Bulk industrial
Phosphate rock is the source of phosphorus fertilisers, a food-security commodity, and increasingly of purified phosphoric acid for LFP batteries. Morocco (OCP) holds about 70% of the world's reserves and is the largest exporter of rock, acid and fertiliser. Egypt, Tunisia, Senegal, Togo, Algeria and South Africa also produce. The EU lists phosphate rock as a critical raw material.