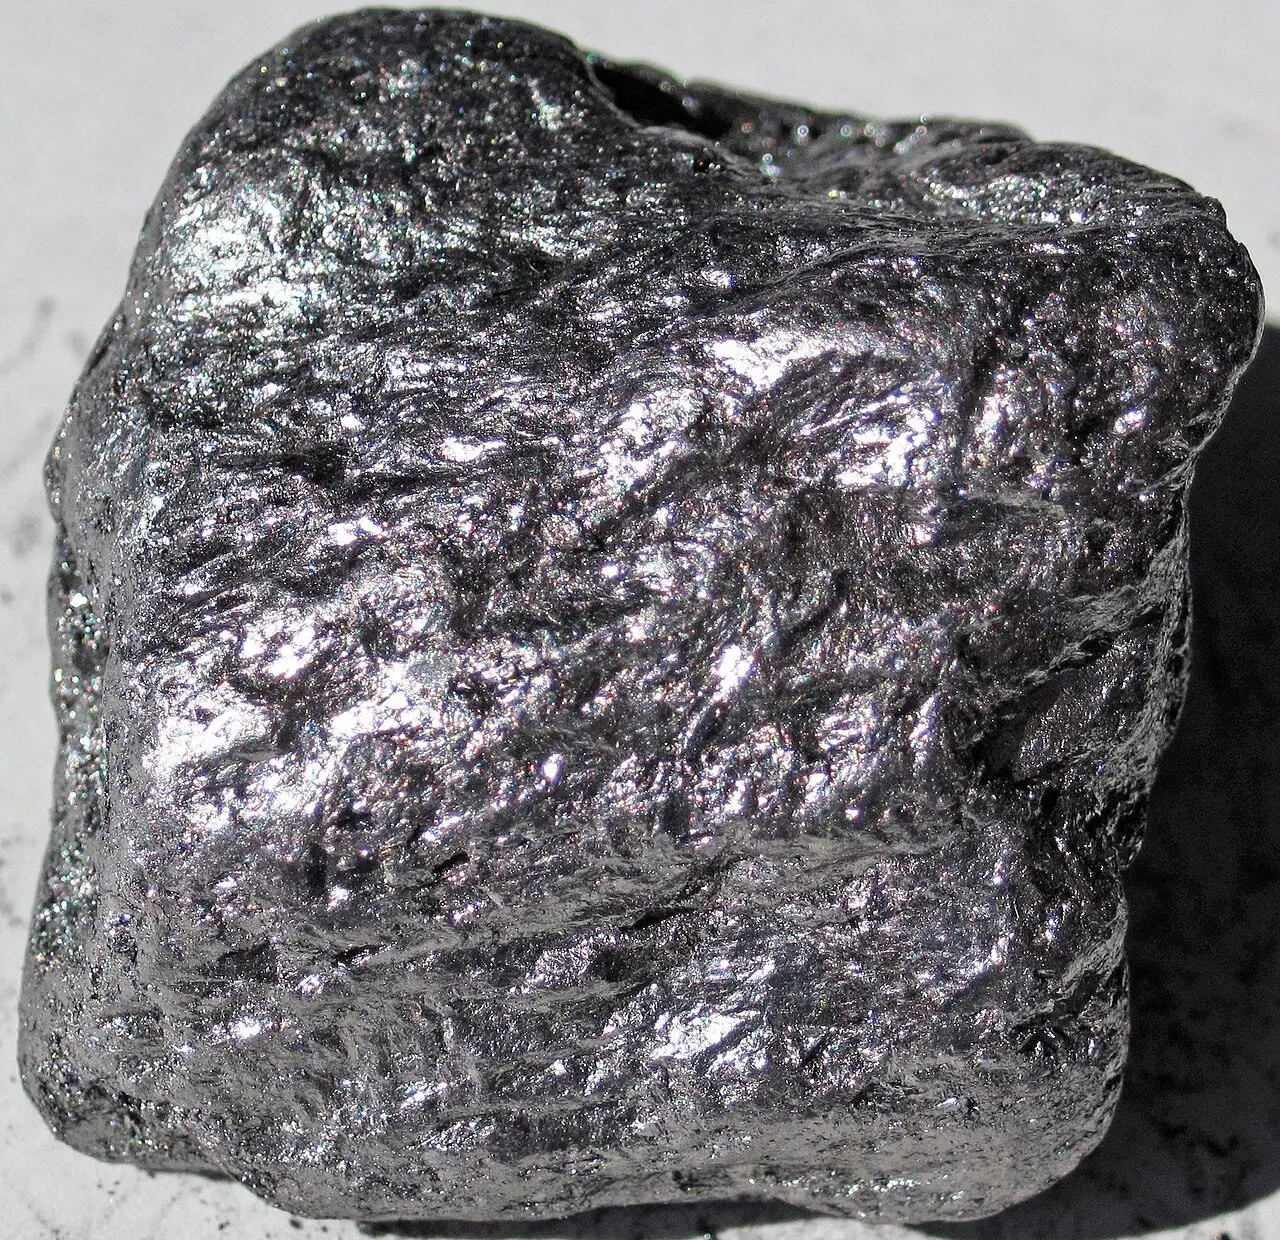
Copper is the backbone of electrification: power grids, EV motors and wiring, renewables and data centres. The DRC is now the world's #2 mine producer after Chile, and Zambia is Africa's #2; together they form the Central African Copperbelt, one of the world's highest-grade copper provinces. Africa exports copper at every stage, from concentrate to refined cathode.
Volumes, origins and terms are shown to verified companies. Availability for everyone else: Spot + Contract. Verify your company or submit a request.
What is traded
Copper cathode
Unit: t · HS 7403.11
refined metal, LME Grade A: ≥99.99% Cu (BS EN 1978 Cu-CATH-1 / ASTM B115). Full plates ~125 kg, strapped bundles ~2–2.5 t. Only LME-registered brands are exchange-deliverable; many DRC SX-EW producers sell 'standard' or non-registered cathode at a discount.
Copper concentrate
Unit: t · HS 2603.00
flotation product, typically 20–30% Cu (Kamoa-Kakula concentrate is unusually high at >50% Cu); sulphide mineral powder shipped in bulk or bags; also contains payable Au/Ag and penalty elements (As, Bi, Hg, Pb).
Blister / anode copper
Unit: t · HS 7402.00
~98–99% Cu from a smelter (e.g. Kamoa-Kakula's direct-to-blister smelter, 2025), sold to refineries.
Copper-cobalt ores and 'copper oxide' material
Unit: t
typical of the DRC; usually processed locally (SX-EW).
Uses
Electrical wire and cable (~60%)
Power grids and transformers
EVs (≈3–4× the copper of an ICE car)
Renewables
Construction
Electronics
ARAM sourcing assessment
High. Deep, liquid market; Africa is central. Best entry point: cathode from mid-tier DRC/Zambian SX-EW producers (off-take or spot tonnages), and concentrate for smelters. Listing status: Spot available + Contract.
Producing countries — DR Congo, Zambia, South Africa, Zimbabwe
DR Congo
Zambia
South Africa
Zimbabwe
Producers, mines and projects
DR Congo
Katanga/Lualaba — Kamoa-Kakula (Ivanhoe/Zijin), Tenke Fungurume and Kisanfu (CMOC), Kamoto/KCC and Mutanda (Glencore), Sicomines, Deziwa; many mid-size SX-EW plants
Zambia
Kansanshi and Sentinel (First Quantum), Mopani (IRH), Lumwana (Barrick), Konkola
USGS Mineral Commodity Summaries 2026 — African rows of the world production & reserves table
World Mine and Refinery Production and Reserves: Reserves for Canada, Chile, Peru, Poland, and “Other
Congo (Kinshasa) 2,990 3,200 2,560 2,800 80,000
Zambia 823 940 189 270 21,000
World total (rounded) 23,000 23,000 27,600 29,000 980,000
Exports reported by African countries
Year
Country
HS
Value
Net weight
2024
DR Congo
7403
$23.78bn
2.59 Mt
2023
DR Congo
7403
$17.02bn
2.02 Mt
2024
Zambia
7402
$5.84bn
621.4 kt
2023
Zambia
7402
$5.03bn
579.6 kt
2024
DR Congo
2603
$2.71bn
926.7 kt
2023
DR Congo
2603
$2.16bn
790.3 kt
2024
Zambia
7403
$1.67bn
180.6 kt
2023
Zambia
7403
$1.63bn
199.8 kt
2023
DR Congo
7402
$1.41bn
183.7 kt
2024
DR Congo
7402
$1.31bn
160.8 kt
2024
South Africa
7403
$495.4m
59.6 kt
2023
South Africa
7403
$491.7m
—
Imports from Africa reported by buyers
Mirror data fills gaps where exporters report late or incompletely.
Year
Buyer
Origin
HS
Value
Net weight
2024
China
DR Congo
7403
$14.01bn
1.48 Mt
2023
China
DR Congo
7403
$7.41bn
870.3 kt
2024
China
Zambia
7402
$3.96bn
422.4 kt
2023
China
Zambia
7402
$3.42bn
405.4 kt
2024
China
DR Congo
2603
$2.52bn
624.8 kt
2023
China
DR Congo
2603
$2.08bn
568.2 kt
2023
India
Zambia
7402
$1.73bn
203.9 kt
2024
India
Zambia
7402
$1.59bn
179.0 kt
2023
China
DR Congo
7402
$1.41bn
172.6 kt
2024
China
DR Congo
7402
$1.12bn
123.8 kt
2023
UAE
DR Congo
7403
$1.10bn
126.2 kt
2024
Rep. of Korea
DR Congo
7403
$937.4m
102.3 kt
Source: UN Comtrade (public data). Values in US$.
How it is priced
Cathode: LME Copper cash/3-month price plus a physical premium (e.g. Rotterdam or Shanghai premium); non-registered brands at a discount
Concentrate: LME price × payable Cu (typically 96–96.5% after a 1-unit deduction) minus treatment and refining charges (TC/RC, set annually by major miners and Chinese smelters; hit record lows in 2024–25) and impurity penalties
Blister: LME less refining charge
Commercial terms
Minerals trade on formula prices: a published benchmark × metal content × payable percentage, less treatment charges and impurity penalties, settled on independent assay. Payment is typically by documentary letter of credit, with 90–95% provisional payment against shipping documents and the balance on final assay.
Cathode: chemical composition certificate per BS EN 1978 / ASTM B115; brand registration documents
Concentrate: sampling per ISO 12743; Cu by electrolytic or titration methods; Au/Ag by fire assay; moisture ISO 10251; umpire on splitting limits
Logistics
Cathode: containerised or breakbulk, trucked from Katanga to Durban, Dar es Salaam, Walvis Bay or via the Lobito rail corridor
Concentrate: IMSBC Code cargo — often Group A (may liquefy): transportable moisture limit (TML) certificate required before loading
Export rules by country
DR Congo
State marketing channel
export via approved channels; strategic-minerals regulator ARECOMS; state trading entity (EGC for cobalt) and moves to market state-share output (reported 2025)
Authority: ARECOMSReported — verify before relying on itSource
Zambia
Levy / tax
Mercuria–IDC copper trading JV (Dec 2024); export taxes and permits
LME Grade A copper cathode must meet BS EN 1978:2022 Cu-CATH-1 (or ASTM B115 Grade 1); ≥99.99% Cu with tight impurity limits (e.g. Ag ≤25 ppm, total non-Cu ≤65 ppm). Full-plate cathodes ~914×914 mm, bundles ~2 t. Only LME-registered brands deliverable on LME.
Kamoa-Kakula (DRC, Ivanhoe/Zijin/DRC state 20%): 2024 output 437,061 t Cu in concentrate; 2025 guidance 520–580 kt (later revised); on-site 500 ktpa direct-to-blister smelter started Nov 2025, first anode Dec 2025. Power constraints from regional drought.
Research compiled September 2026 from USGS, UN Comtrade, producer and regulator publications. Facts marked “reported” come from secondary sources and should be confirmed before contracting.
On the ground · Copper
The mines behind the supply.
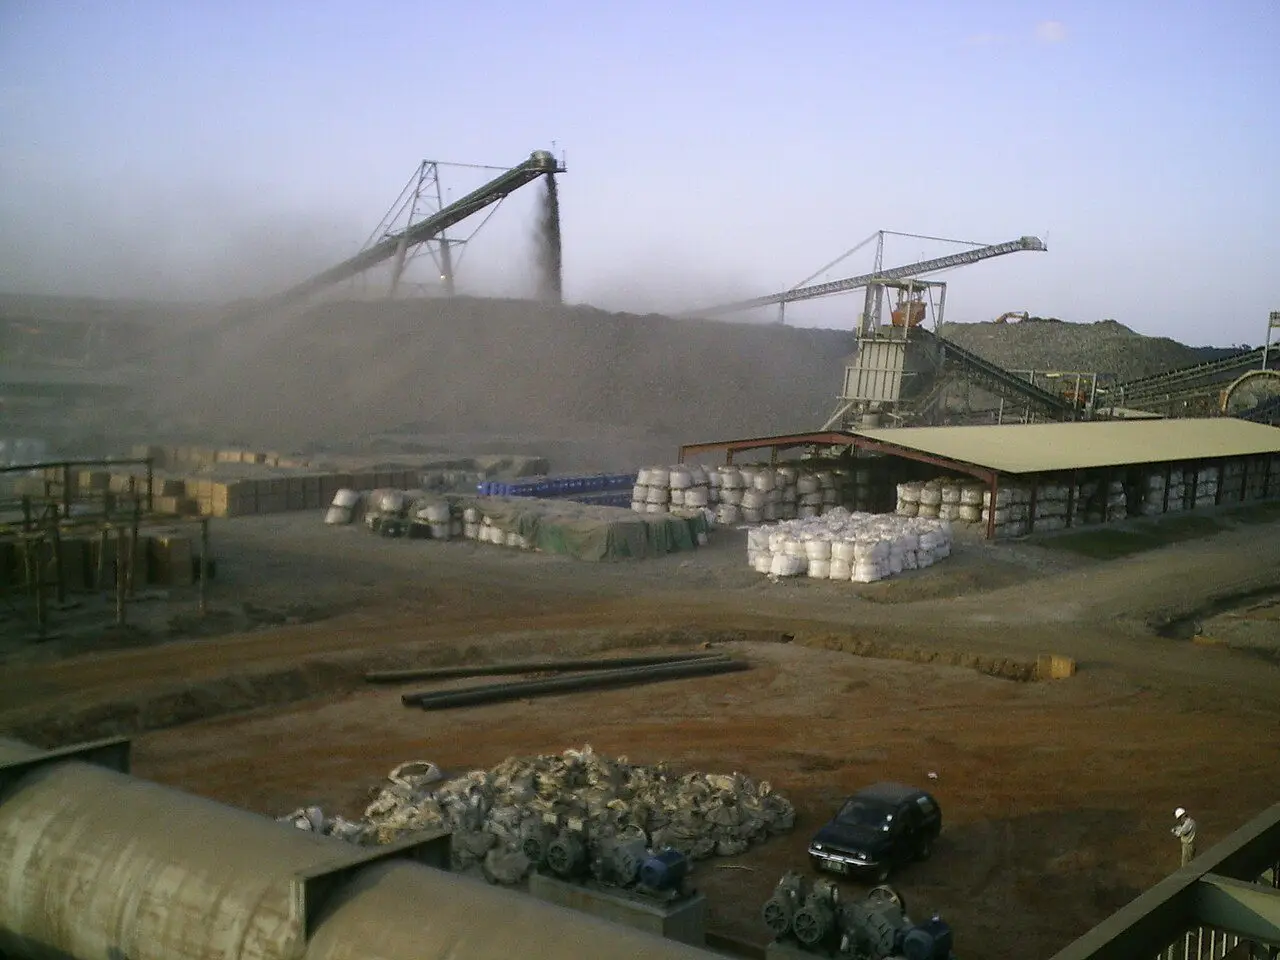
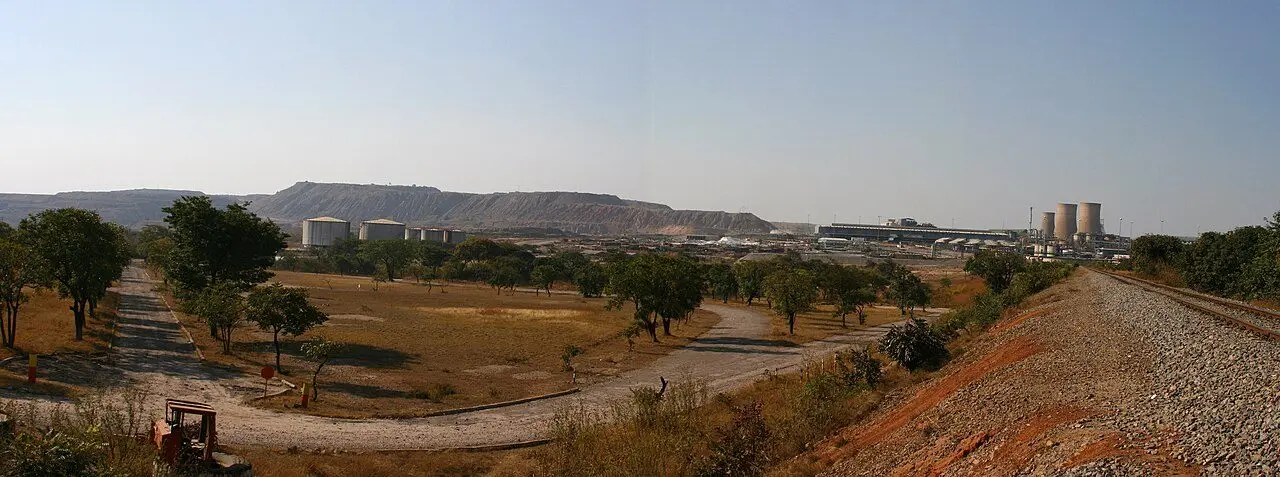
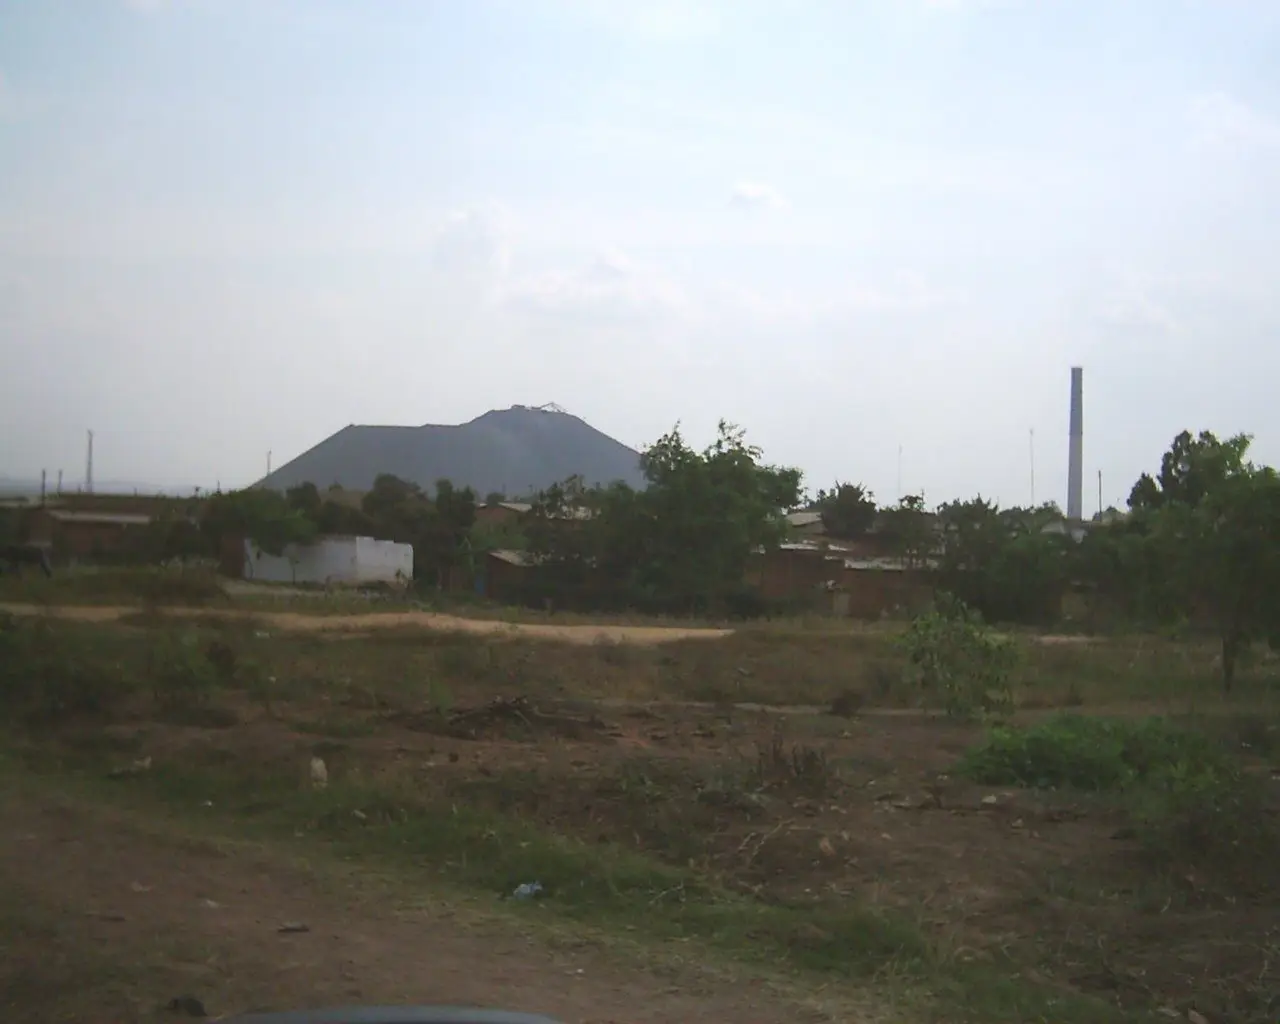
The mines and districts that define supply, with their operators. They are shown for geographic context: third-party operations, not ARAM sites, and not the source of any particular lot. Ownership and status as publicly reported in 2026.
Producing mine and smelter
Zambia
Kansanshi
Operated by First Quantum Minerals
Zambia's largest copper mine, in North-Western Province, with its own smelter.
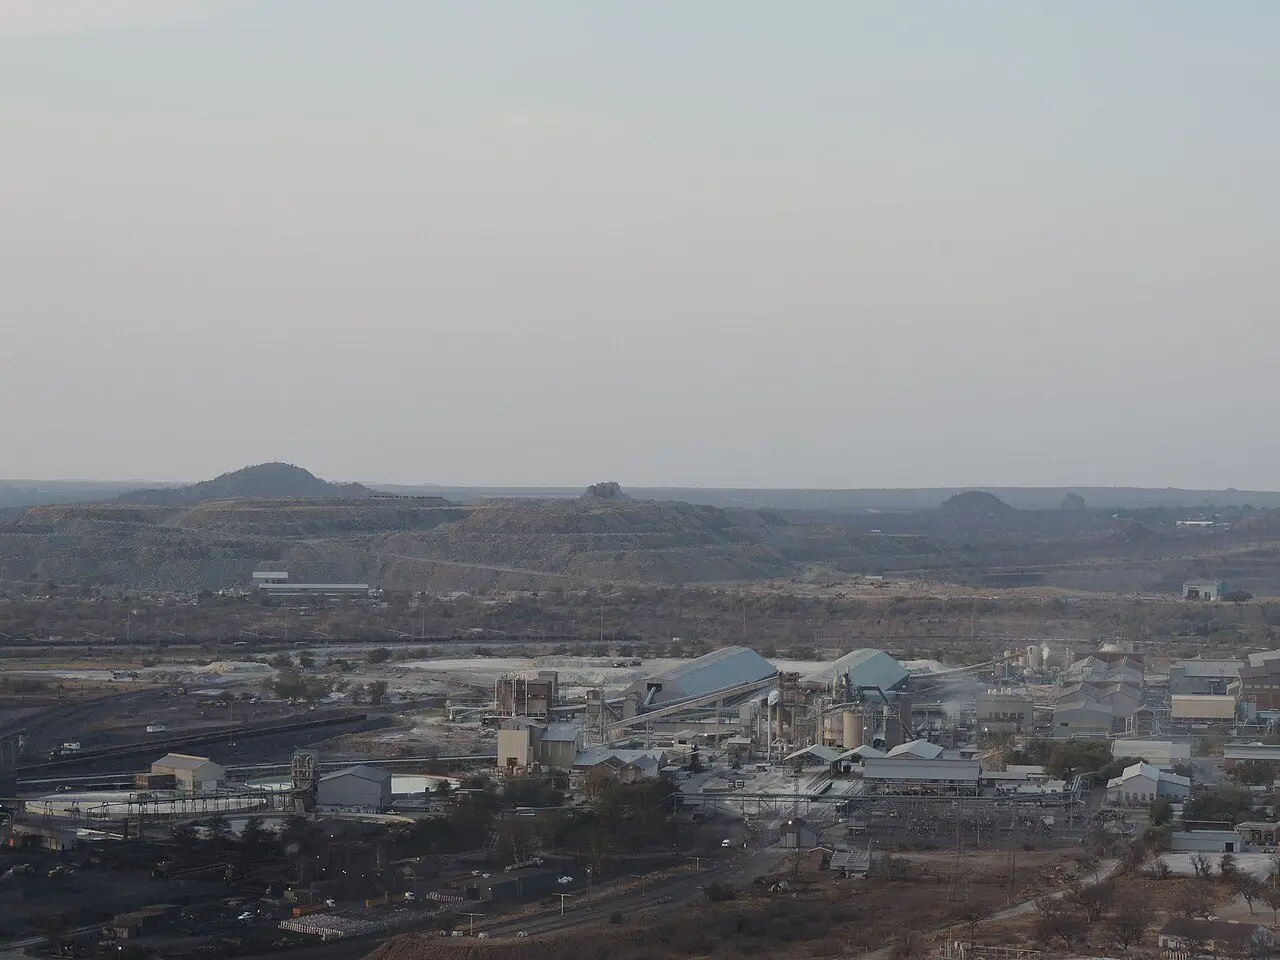
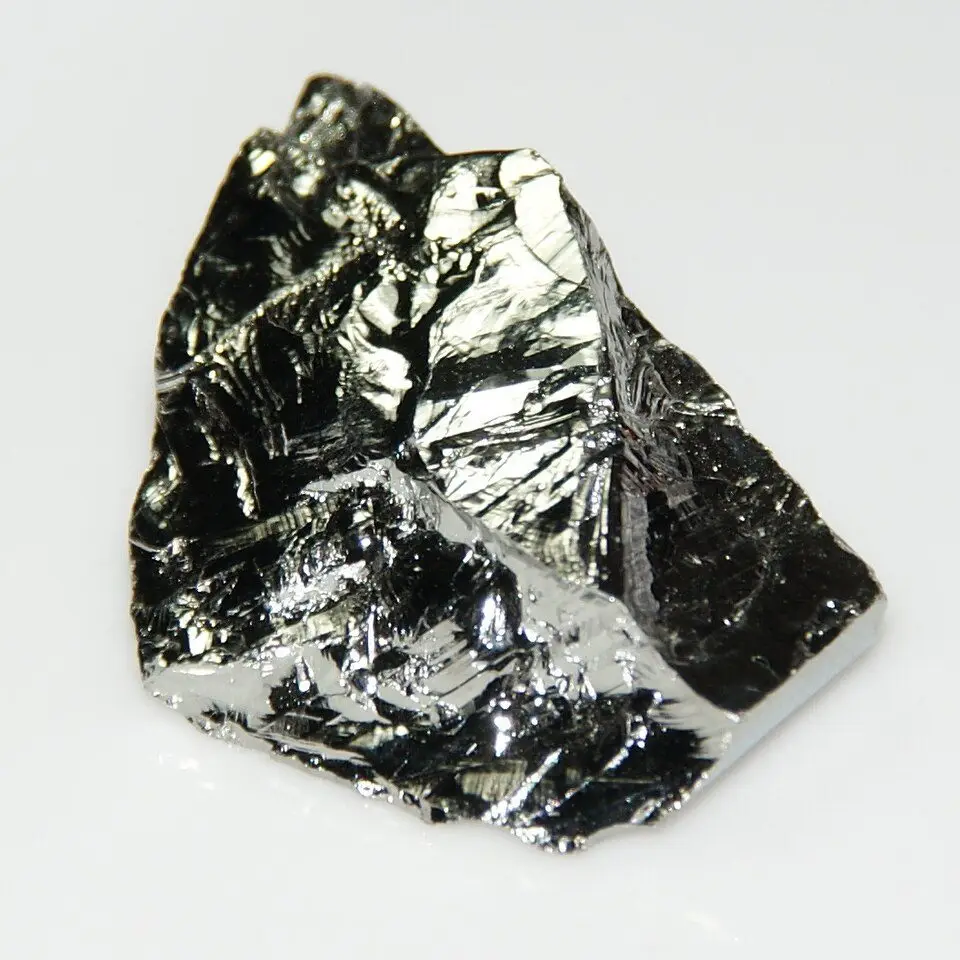
Decades of slag and tailings from Gécamines' Lubumbashi smelter, now reprocessed for germanium, copper and cobalt; the first germanium concentrate shipped in 2024.
A carbonatite complex hosting one of Africa's largest open pits (copper), phosphate operations (Foskor) and rare earths recoverable from phosphogypsum stacks.
Operated by Ivanhoe Mines, Zijin Mining, Government of the DRC
One of the world's highest-grade large copper mines, in Lualaba province. A direct-to-blister smelter started in late 2025, shifting exports from concentrate towards anode copper.
DR Congo
No freely licensed photograph
Producing mine
DR Congo
Tenke Fungurume
Operated by CMOC Group
A major copper-cobalt operation in Lualaba; together with CMOC's Kisanfu it makes CMOC the world's largest cobalt producer.
DR Congo
No freely licensed photograph
Mining district
DR Congo
Kolwezi mining district
Operated by Multiple operators (Glencore's KCC, state-linked and Chinese-owned producers)
The centre of the Central African Copperbelt's cobalt output, with large industrial mines and artisanal diggings side by side — the setting behind cobalt due-diligence requirements.
Reference specimens
Darla Sondrol, CC0
Photo by and (c)2015 Derek Ramsey (Ram-Man), CC BY-SA 4.0
Didier Descouens, CC BY-SA 3.0
Photo by and (c)2015 Derek Ramsey (Ram-Man), CC BY-SA 4.0
“Jon Zander (Digon3)", CC BY-SA 3.0
Photo by and (c)2015 Derek Ramsey (Ram-Man), CC BY-SA 4.0
Darla Sondrol, CC0
Didier Descouens, CC BY-SA 4.0
JJ Harrison (https://www.jjharrison.com.au/), CC BY-SA 3.0
Kaethe17, CC BY-SA 4.0
Kaethe17, CC BY-SA 4.0
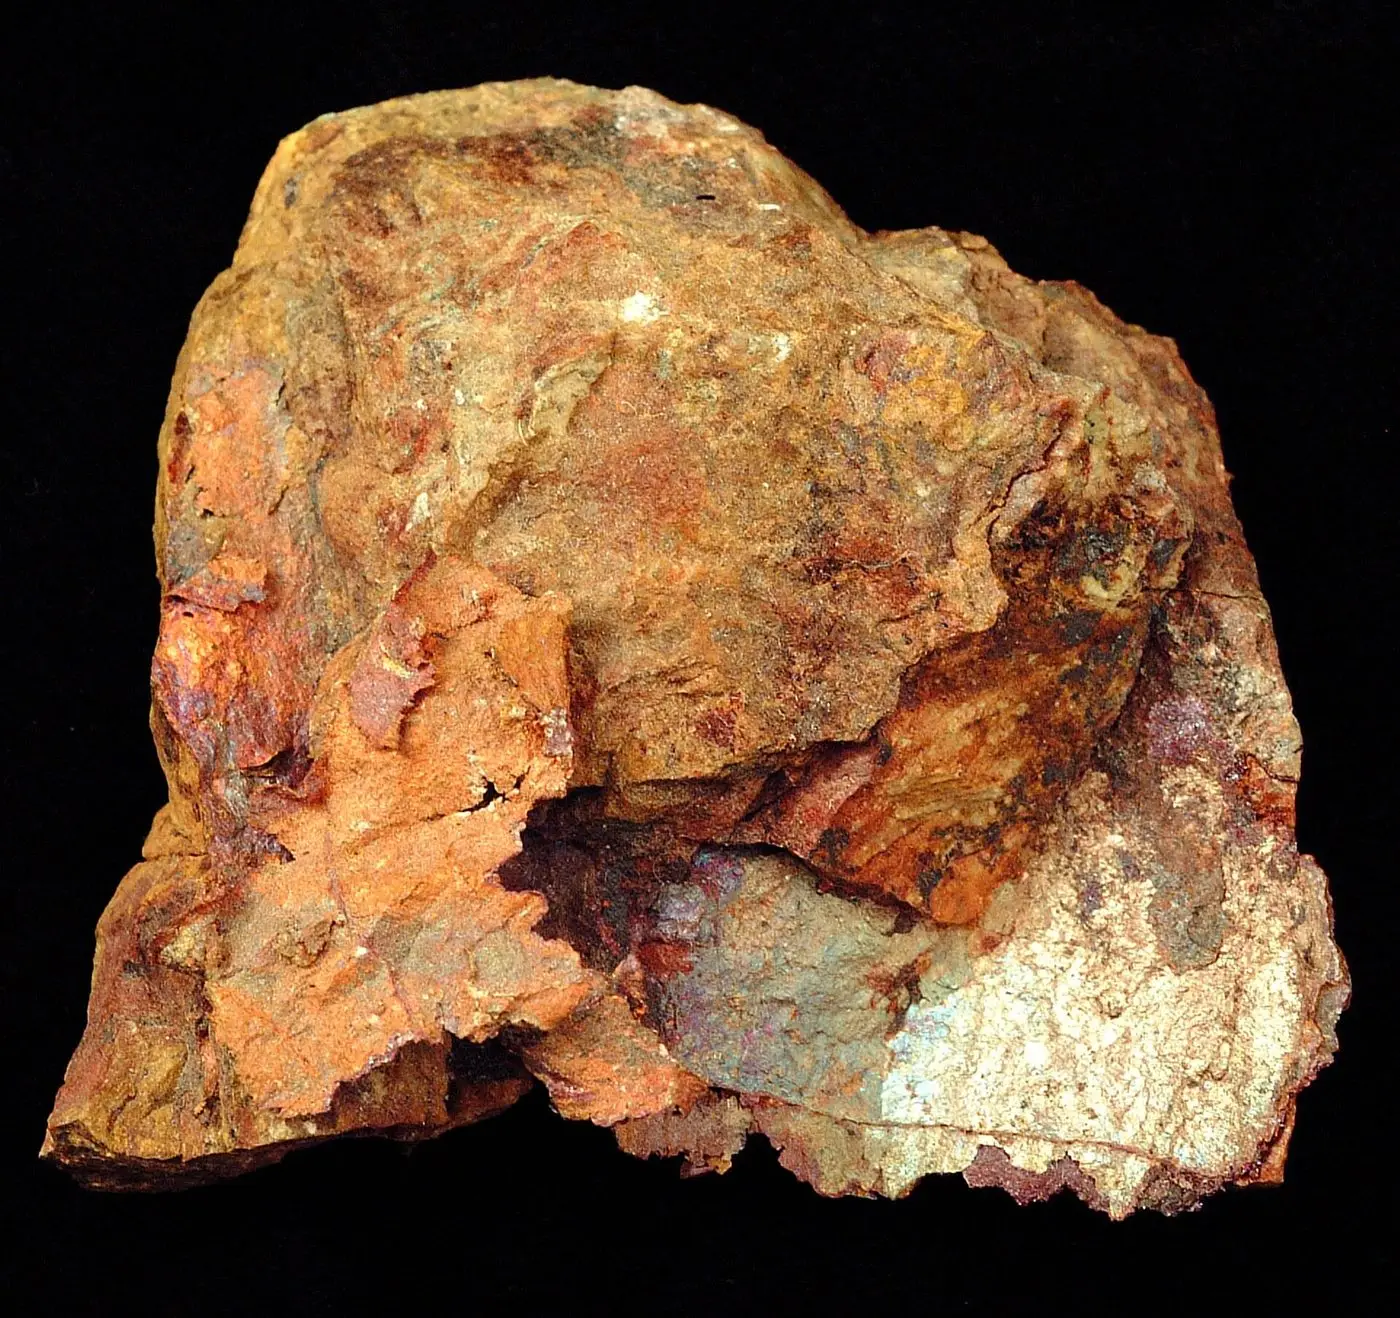
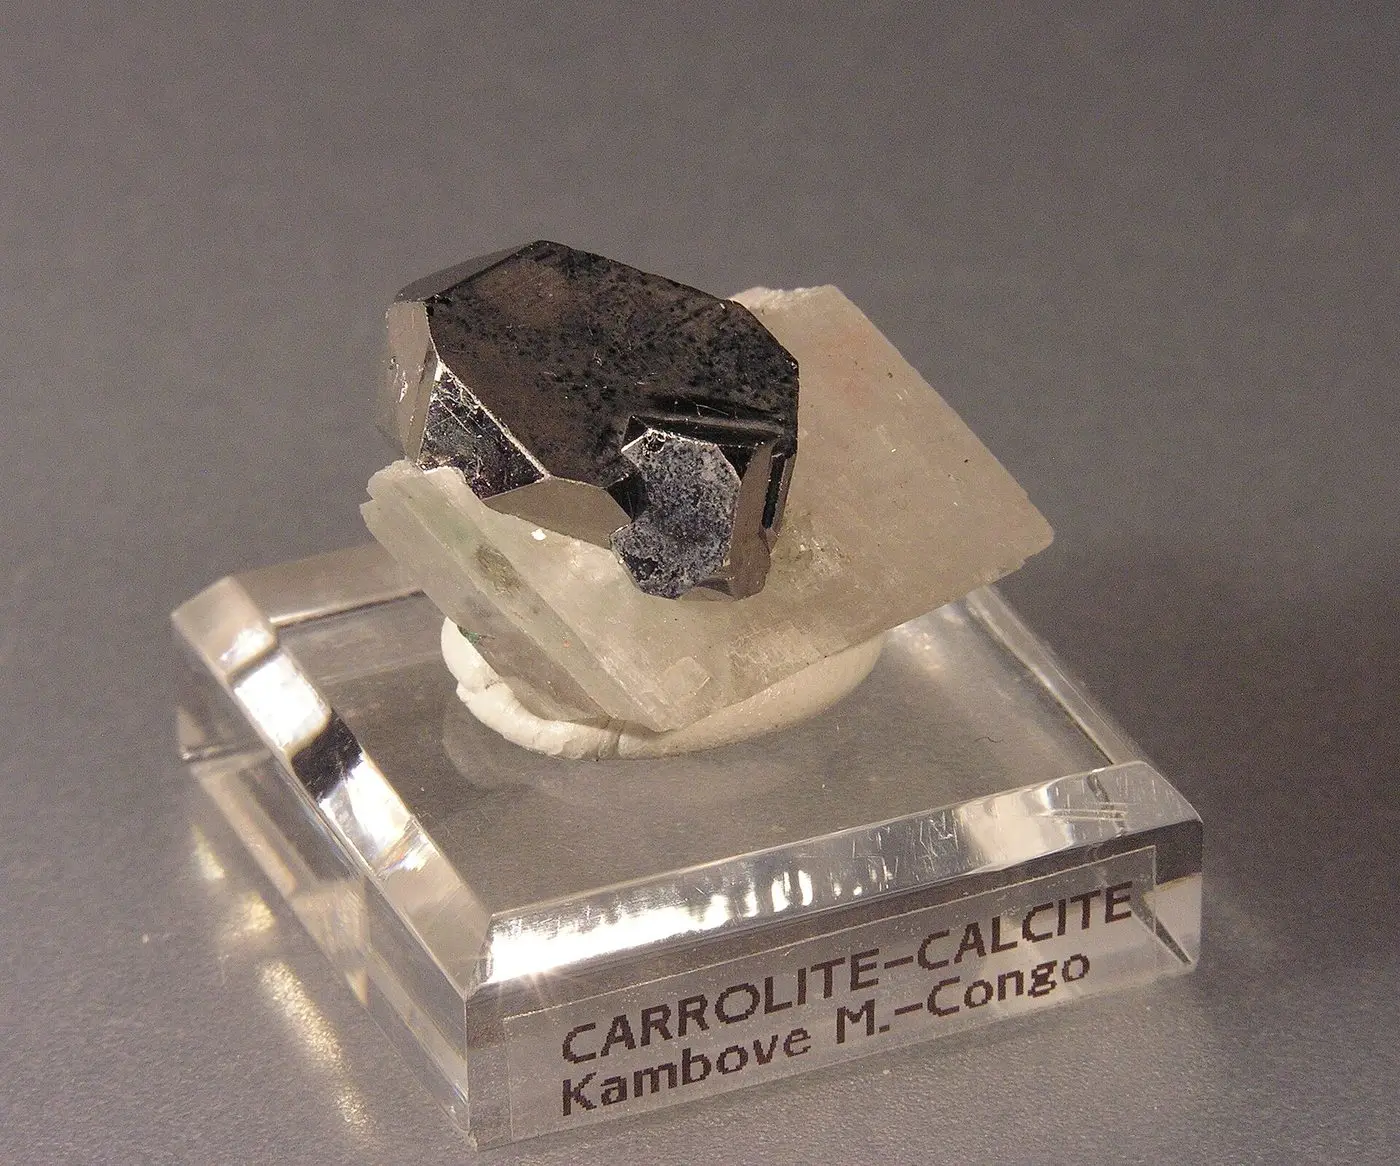
Reference specimens of the ore minerals and products, from public collections. They illustrate the material, not a specific ARAM lot or source.